Health
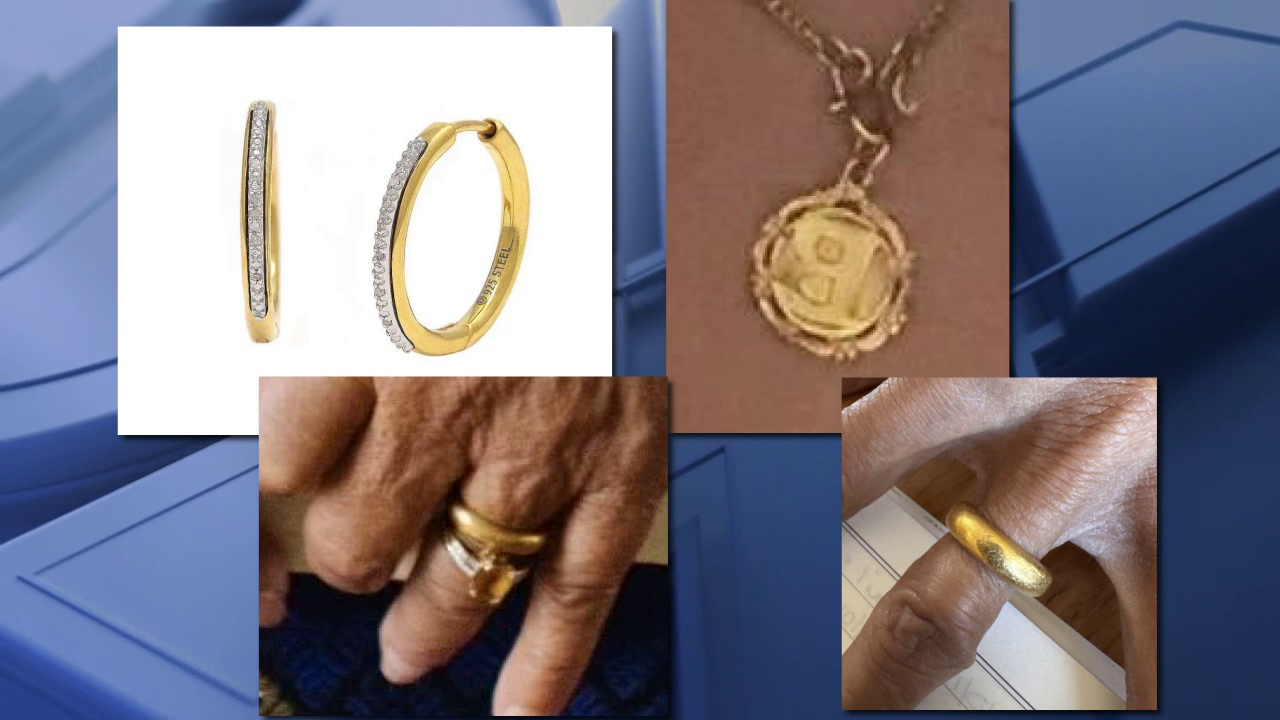
Apple Valley family devastated by missing heirloom jewelry after mother's death
By Marcus Chen
Advertisement · Why this ad?
Katherine oversees editorial operations across all six brands. Before joining The Meridan Group, she spent 14 years at the Minneapolis Star Tribune, where she led the metro desk through its digital transformation. She holds a Master's in Journalism from Northwestern's Medill School.
More from Katherine →
As November approaches, many families in Minneapolis are preparing for the annual ritual of health insurance open enrollment. For the Johnson family, this time of year brings a mix of anticipation and anxiety. Last year, they chose a plan that seemed to suit their needs, but unexpected medical expenses left them questioning their decision. This year, they are determined to navigate the complexities of the insurance landscape with a more informed approach.
The open enrollment period for health insurance begins on November 1 and runs until December 15 for those purchasing coverage through state-based marketplaces and HealthCare.gov. For those who enroll by December 15, coverage will commence on January 1, 2027. However, the standard open enrollment period extends until January 15, allowing additional time for those who miss the initial deadline to secure coverage that will take effect on February 1.
It is important to note that individuals covered by Medicare have their own open enrollment period that overlaps with the marketplace enrollment windows. Meanwhile, many employer-sponsored insurance plans typically have open enrollment periods in October and November, further complicating the landscape for those evaluating their options.
Mychal Winter, president of the National Association of Benefits and Insurance Professionals (NABIP), emphasizes that open enrollment can be overwhelming for families. With healthcare affordability at the forefront of national discussions, especially during midterm elections, it's crucial for households to seek guidance from insurance professionals. Winter advises that taking a proactive approach is key to making the right choice.
One of the first steps families should take before choosing a health insurance plan is to review their healthcare spending over the past year. Winter suggests that households should examine their previous healthcare expenditures to anticipate future needs. This reflection can provide valuable insight into the types of coverage that may be necessary moving forward.
Families like the Johnsons should consider not only their past medical expenses but also any upcoming changes in their health. For instance, if a family member is expecting a baby or if there are chronic conditions that require ongoing care, these factors will influence the choice of plan. By forecasting potential healthcare needs, families can select a plan that aligns with their requirements and financial situation.
Moreover, understanding the overall healthcare landscape, including the impact of inflation on medical costs, is essential. Families must consider how rising healthcare costs could affect their premiums and out-of-pocket expenses. This comprehensive evaluation will help them make informed decisions during the enrollment process.
In addition to reviewing past healthcare spending, families must also evaluate potential changes in health insurance premiums. Winter notes that premiums are expected to rise due to inflation and increased healthcare costs. It is critical for families to compare last year’s premiums with the anticipated costs for the upcoming year.
For the Johnsons, this means not only assessing their budget but also determining whether their previous plan remains financially viable. They must weigh the premium increases against their healthcare needs to ensure they select a plan that fits within their financial framework. This careful consideration can help families avoid unexpected financial strain in the coming year.
Another vital aspect of choosing a health insurance plan is understanding the network of healthcare providers associated with each plan. Doctors and healthcare professionals may change their contractual relationships with insurance plans from year to year. As a result, it is essential for families to verify whether their preferred doctors and specialists remain in-network.
Winter cautions that failing to check the network status of healthcare providers could lead to unexpected out-of-pocket costs. Families may find themselves needing to switch doctors if their current providers are no longer covered by their chosen plan. For families like the Johnsons, maintaining continuity of care with their established healthcare providers is a priority, making this step critical in their decision-making process.
Choosing a plan from a preferred provider organization (PPO) can provide more flexibility in selecting doctors and specialists without requiring referrals. However, this flexibility often comes at a higher cost, which families must factor into their overall budget.
When evaluating health insurance plans, families must also consider out-of-pocket costs, including deductibles, co-payments, and other expenses associated with healthcare services. Winter highlights that many individuals opt for high-deductible plans to lower their monthly premiums, but this strategy requires careful consideration of whether they can afford the deductible when medical needs arise.
The Johnson family, for instance, may find that while a high-deductible plan offers lower monthly payments, it could pose a financial challenge if they experience significant medical expenses. Understanding the balance between premium costs and potential out-of-pocket expenses is crucial for families as they navigate their options.
Additionally, families should explore health savings accounts (HSAs) associated with high-deductible plans. HSAs allow individuals to save money on a tax-free basis for qualified medical expenses, providing a valuable tool for managing healthcare costs. Funds in an HSA can be used to cover deductibles and other out-of-pocket expenses, making them a beneficial option for families looking to save for future healthcare needs.
As families prepare to make their health insurance selections, access to reliable resources is essential. The Minnesota Department of Health provides a wealth of information on health insurance options available to residents. Their website includes details on the open enrollment process, plan comparisons, and guidance on how to choose the right coverage.
Additionally, organizations like NABIP offer educational resources and professional assistance to help families navigate the complexities of health insurance. Seeking support from knowledgeable professionals can alleviate the stress associated with open enrollment and empower families to make well-informed decisions.
Community organizations and local health departments also play a vital role in providing information and support during this process. Families should take advantage of workshops, webinars, and informational sessions that can enhance their understanding of available options and help them feel more confident in their choices.
The open enrollment period presents an opportunity for families to reassess their healthcare needs and make informed decisions about their coverage. For the Johnsons and other households in Minneapolis, this year’s enrollment is particularly significant as they strive to secure a plan that aligns with their financial and medical requirements.
With rising healthcare costs and evolving health needs, families must approach this process with diligence and foresight. By reviewing past expenditures, evaluating potential changes in premiums, and understanding their healthcare networks, families can make choices that will benefit them in the long run.
As the open enrollment window approaches, it is essential for families to remain proactive and informed. With the right resources and support, Minneapolis residents can navigate the complexities of health insurance and secure coverage that fosters health and well-being for their families.
By Marcus Chen
By Marcus Chen
By Marcus Chen
By Katherine Langford